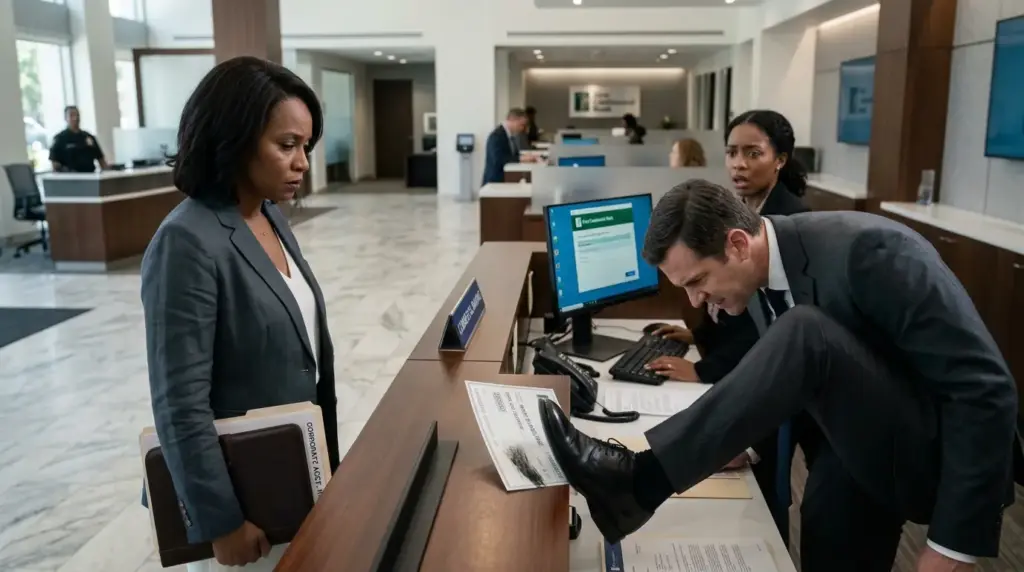
According to Heritage, the branch had initiated heightened review of an atypical transaction. The customer then chose not to complete the verification process and removed the instrument before review could be concluded. The racial insult was addressed separately as alleged employee misconduct.
That wording divided one event into two pieces: Martin’s behavior became a personnel concern; the fraud referral became ordinary risk management.
I sent Marion the response. She called me less than a minute later.
“They’re saying I stopped verification.”
“They are.”
“Keep the issuing bank confirmation with the complaint.” That was all she asked.
We filed the formal complaint that afternoon.
Two days later, Alicia Grant contacted our outside counsel through the number on the incident notice. She did not send internal bank records. She gave a factual statement about what she had personally handled: her teller screen had shown no instrument alert before Martin intervened; Marion had provided the documents requested; Alicia had prepared to authenticate the check; Martin stopped that process and later instructed her to close the transaction as “customer declined verification”; she had refused to enter that description.
The next line in Alicia’s statement raised the stakes: her customer-facing access had been suspended pending an internal conduct review. She was still employed; she was no longer working the counter.
That gave the complaint a second consequence stemming from the same original decision. The bank was no longer dealing only with a disputed customer transaction; it was now reviewing the employee who would not make the record agree with management’s version.
Rachel Donnelly entered the case through the Federal Fair Banking Review channel. I met her for the first time in a conference room at Southline.
She did not ask Marion to repeat Martin’s insult; she already had the written account. Her first question concerned the referral: “What objective condition existed before the manual risk review was opened?”
We gave her everything Southline controlled: the onboarding packet, the check information, First Continental’s confirmation, the branch disposition. Alicia’s statement went through counsel separately. Heritage had to answer the rest.
Several days later, Rachel requested a meeting after the bank produced its regional risk guidance. I read the relevant page once: branch managers were permitted to apply heightened review when transaction characteristics or “client presentation” created an atypical risk profile.
There was no definition beside “client presentation”—no document type, no transaction threshold, no observable condition, just discretion.
Rachel asked whether we had ever seen the phrase before. We had not.
Then she showed us the name attached to an older internal compliance submission: Caroline Mays.
Caroline had worked in regional compliance before leaving Heritage nearly two years earlier. Her report had examined manual fraud referrals across comparable commercial transactions. It did not claim every referral was improper. It compared similar transaction bands, account documentation, and product types. The difference appeared in who was selected for additional review: Black and Latino customers were being referred at materially higher rates, even when transaction characteristics and documentation were comparable. Caroline had identified the undefined presentation criterion as a control weakness. Her report had been acknowledged; the rule remained.
For the first time, Marion leaned back from the table. The check had already been proven valid. Now we knew the question was larger than whether Martin had disliked the way she looked. Her treatment fit a decision category the bank had already been warned could produce unequal scrutiny.
Heritage responded that branch managers needed discretion to prevent fraud. They also said Martin had historically been rated well for loss prevention.
That defense did not remove the problem; it connected his judgment to the system that rewarded it.
Rachel expanded the production request—not to every complaint Heritage had ever received, only to manual referrals using the same presentation-based discretion, the prior findings tied to those referrals, Alicia’s employment action, and the approval history behind the regional guidance.
Until then, Heritage had controlled the language used to describe what happened. That ended with Rachel’s request. The branch could still defend its decision; it could no longer define the question.
Rachel Donnelly’s final findings began with one question: What fact existed before Martin Heller opened the manual risk review?
Heritage National had produced the transaction file, the regional guidance, Martin’s branch notes, prior complaint summaries, and the earlier compliance work completed by Caroline Mays. None of those records identified a defect in Marion Caldwell Price’s check. There had been no issuer warning, no identity mismatch, no document problem, no unusual account history—because the commercial account had not even been opened yet. The only discretionary factor Martin had cited before stopping Alicia Grant’s verification process was the way the customer and transaction presented.
Rachel did not treat that language as proof by itself; she compared it with the records that followed. Caroline’s earlier review had already found that Black and Latino commercial customers were being selected for manual fraud review at higher rates than comparable customers with similar transaction sizes and documentation. Heritage had acknowledged that report; it had not removed the presentation criterion, nor had it defined an objective threshold for using it. Managers were still allowed to turn an impression into a formal review state. Martin had done exactly that.
His racial insult and what he did to the check were handled as individual misconduct. They made his judgment easier to understand, but Rachel’s finding did not depend on them. The procedural failure happened earlier: he had created suspicion before the bank had identified anything suspicious about the transaction.
Heritage tried one final distinction. Its counsel argued that Martin had authority to refer unusual transactions; they also said branch discretion was necessary in fraud prevention.
Rachel agreed with the first half. Then she asked what made Marion’s transaction unusual before the referral. Nobody supplied a transaction-based answer. That ended the argument.